
Ibiza’s Legal Villa Market Is Back at Full Strength. The Rest of the Island Is Half the Size.
In one line: The Ibiza rental market has restored its licensed villa stock to 1,303 listings after two years of licence and registration turmoil that halved the island’s short-let count, and peak season paid 21% more for it, but September is 49% booked against 64% at the same date last year, because owners are asking July prices for shoulder-season nights.
Domundos / Market Reports / September. Monthly analysis of the Ibiza rental market for villa owners. Data: PriceLabs market data (2 September 2026), AirDNA and AirROI market trackers (1 to 3 September 2026), Domundos report archive.
A note on this month’s data. From this report onward we track the full Ibiza rental market for villas with three bedrooms or more, 1,303 active listings as of 2 September. Previous reports used a smaller set centred on Jesús that included apartments and covered roughly 1,100 listings. The new set matches the market Domundos serves and covers the whole island. Every comparison below is against the same time last year within the new set. Our villa series starts in September 2024, after the island’s clean-up of unlicensed listings had already begun, so the 2024 and 2025 baselines are depressed by it. Figures from the June, July and August reports are not directly comparable.
TL;DR
- Ibiza has 1,303 active villa listings with three or more bedrooms, 281 more than a year ago (+28%). This is restoration, not growth. The 2024 and 2025 counts were suppressed by the licence and registration clean-up; the licensed villa market has re-listed through 2026 and is back at its proper size
- August closed at 82% occupancy against 84% last year, at an average daily rate of €1,273, up 21%. Revenue per available villa in August rose 15% to €26,042. The returning villas were absorbed in peak season with almost no loss of occupancy
- September is 49% booked against 64% at the same date last year. September’s asking rate is €883 a night, 15% above last year’s €767. Revenue per villa for September is currently flat year on year at €12,100, meaning higher prices are being paid for entirely by fewer nights
- October is pacing 27% against 38%, with asking rates 22% higher than last October. Last October finished at 61%
- Market-wide, the villa segment is up on every trailing KPI: ADR €791 (+14%), RevPAR €504 (+15%), bookings 32,380 (+17%), booking window 57 days (+7), estimated revenue per listing €126,700 (+10%)
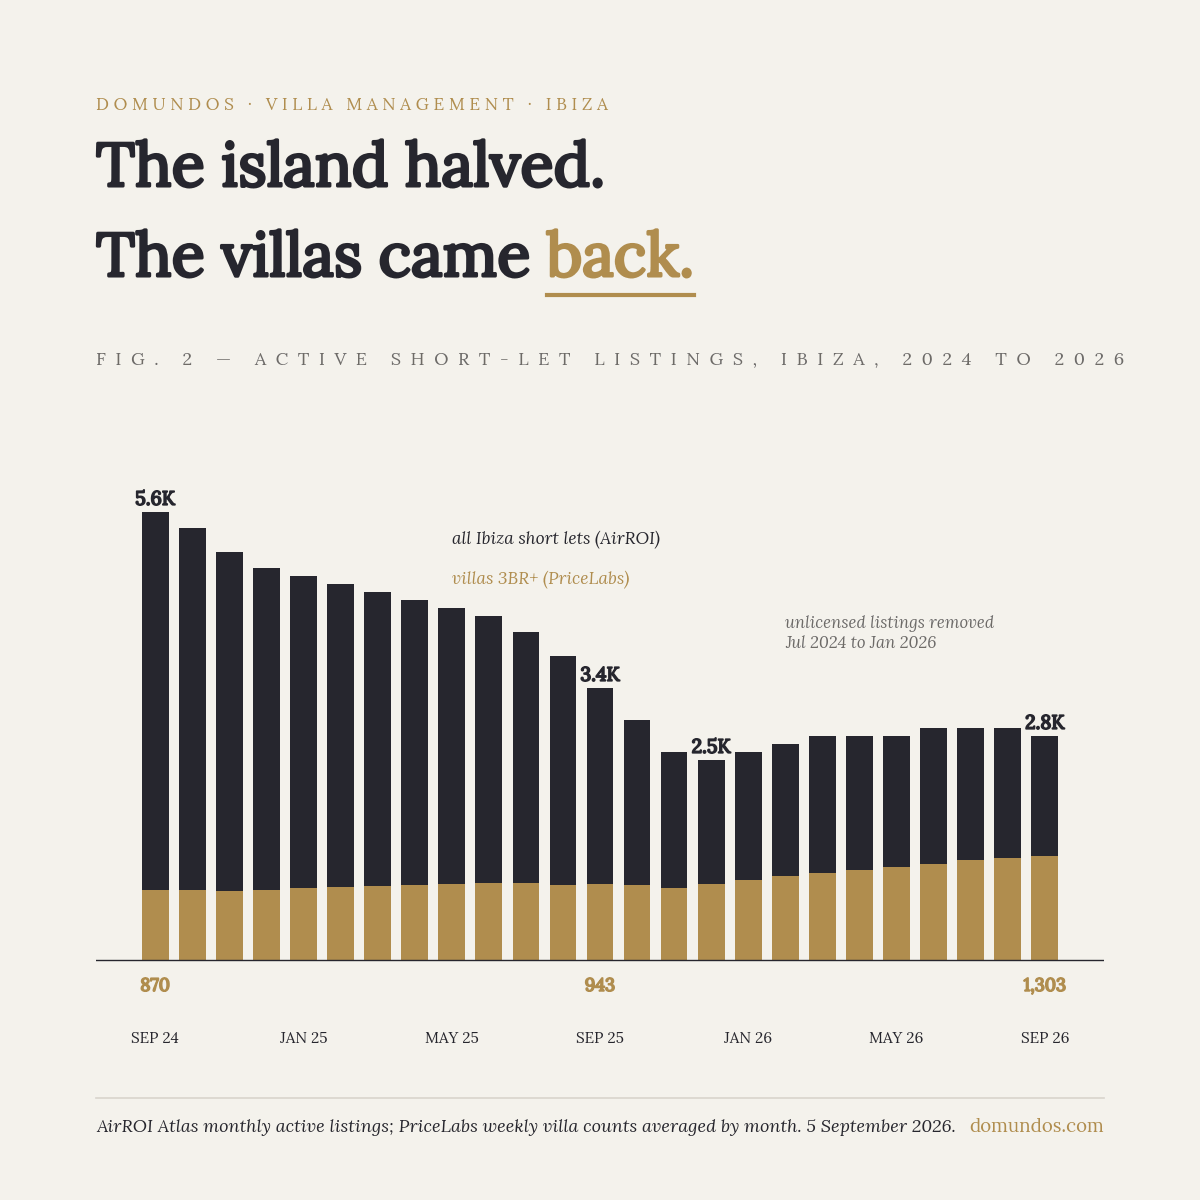
- The whole Ibiza short-let market has halved while the licensed villa segment recovered. AirROI counted 5,600 active listings across Ibiza in September 2024, 3,800 by September 2025 and 2,500 at the January 2026 low, as unlicensed homes were removed from the platforms. The island-wide count is 2,800 today, half of two years ago. Villas with three or more bedrooms: about 870 in autumn 2024, 943 a year ago, 1,303 now
Market Conditions: The Ibiza Rental Market Is Restoring, Not Growing
The most important number in this report is 281, and the most important thing to understand about it is that it is not new supply. There are 1,303 three-bedroom-plus villas active on the Ibiza rental market today, 28% more than at the same point last year. PriceLabs’ weekly count sat between 860 and 980 from September 2024 through the end of 2025 and has climbed in every month of 2026: 1,000 by January, 1,100 by March, 1,200 by June, 1,300 by the end of August. Read on its own, that looks like a boom. Read against the rest of the island, it is a recovery.
The two years before it were the clean-up. AirROI counted 5,600 active short-let listings across Ibiza in September 2024. The count fell every single month after that, to 3,800 by September 2025 and a low of 2,500 in January 2026, as the Consell d’Eivissa’s enforcement drive, its agreement with Airbnb and the registration-number requirement that took effect on 1 July 2025 stripped unlicensed homes from the platforms. Airbnb alone went from 4,324 Ibiza listings in July 2024, 2,831 of them without a registration number, to 2,051 by September 2025, all of them registered. The island-wide count has crept back to 2,800 since, half of what it was two years ago.
Licensed villas were caught in the same turbulence. Listings were suspended while registration numbers were sorted out, owners held properties back rather than risk a fine, and homes went dark for a season. The 2024 and 2025 villa counts this report compares against were suppressed by that mess, which is why 281 villas can appear in a single year without a single new house being built. Through 2026, with the registration process settled and the Supreme Court striking down the national NRUA register on 19 May, the licensed villa market has come back to its proper size. The 281 are villas that returned, not villas that appeared. Every one of the 1,303 now competes only with other licensed villas, on an island with half the short-let stock it had two years ago.
That is why numbers that would otherwise be hard to explain make sense. Putting 28% more inventory into a market normally drives price down or occupancy down, and often both. In peak season, Ibiza did neither. August closed at 82% occupancy against 84% last year, a two-point gap that is well inside normal variation, at an average daily rate of €1,273, up €218 (21%) on August 2025. Revenue per available villa in August came in at €26,042, up 15%. July told the same story: 86% occupancy, level with last year, at €1,145 a night, up 24%. Total booked nights in the market rose 23% year on year in August, almost exactly matching the rise in listings. Demand did not have to grow to meet new supply. The guests were already there, booking a legal market that had been artificially thin.
The rate gains are not a mix effect. A 3-bedroom villa averaged €653 a night in August, up 18% on last year. A 4-bedroom averaged €1,018, up 16%. A 5 to 6-bedroom averaged €1,519, up 23%. Every size band rose by double digits, which rules out the explanation that the market simply lost its cheaper listings. Comparable villas are charging around a fifth more than they did twelve months ago and filling at the same rate.
Across the whole trailing period the villa segment is up on every headline metric: ADR €791 (+14%), RevPAR €504 (+15%), 32,380 bookings (+17%), a median booking window of 57 days (+7), and estimated revenue per listing of €126,700 (+10%). Occupancy is 64%, one point ahead of last year. For a market that has just re-absorbed more than a quarter of its inventory, these are exceptional figures.
The Feature: Why September Is Not Following the Summer Script
The summer proved that demand in the Ibiza rental market is deep enough to absorb the returning villas at higher prices. September is proving where that depth ends.
At 28 days before the stay month, September 2026 is 49% booked. At the same distance last year, September 2025 was 64% booked, on its way to a final 72%. That is a 15-point gap, the widest we have measured on any month this year. October is 27% booked against 38% at the same date last year, an 11-point gap, with last October finishing at 61%. The first half of September is 54% booked against 70% at this point last year, the second half 46% against 62%. Neither half is on pace.
The gap is not for lack of guests. The number of September bookings in the market already matches last September’s final total. Spread across 28% more villas, level demand produces lower occupancy per villa, which is exactly what the pacing shows. The restored inventory that summer swallowed whole is sitting unsold in the shoulder.
Pricing is making it worse. The September asking rate is €883 a night, 15% above last September’s €767. Listed prices for September nights are up 23% at the median and 36% at the 90th percentile, while the median price actually being paid is up 14%. The gap between what is asked and what is achieved is widening, which is what a market looks like when sellers have not yet noticed that buyers have stopped chasing. Revenue per available villa for September is currently €12,106, against €12,126 at this point last year. Owners have priced September for a 15% rate gain and are receiving it entirely in the form of empty nights.
Cancellation churn adds to the caution. Over the past 30 days the Ibiza rental market recorded 291 cancellations against 297 new bookings for September stays, and 211 against 206 for October. For November through March, cancellations outnumber new bookings by 329 to 127. A September calendar that looks half full today can get emptier before it gets fuller.
The pattern to watch is whether the late surge that rescued July arrives for September. In July, the market booked 19 points of occupancy in the final five weeks. September historically books about 8 points in its final four weeks (last year it went from 64% to 72%). Even a strong late September would leave the month around 57% to 60%, well short of last year’s 72%. The arithmetic does not support holding rate.
One operational signal from the same data points the same way. Listings with an active dynamic pricing strategy make up 37% of the market and take 43% of bookings. Listings with no pricing strategy also make up 37% of the market and take 33%. Responsive pricing is winning share, static pricing is losing it, and September is where a rate set in spring costs the most.
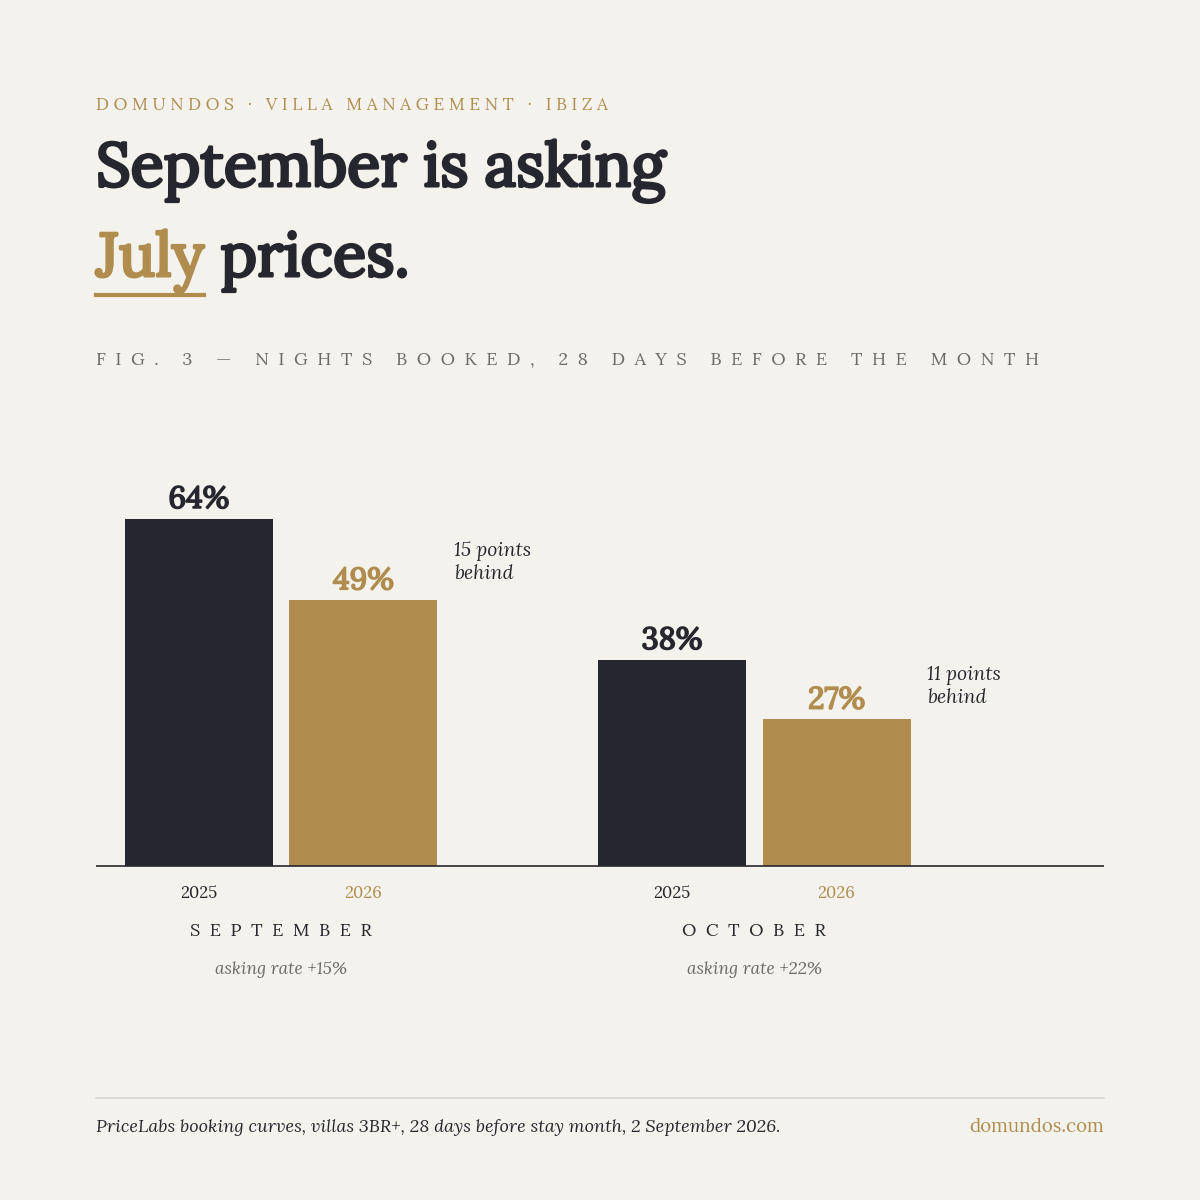
From the Front Line: What We Are Seeing at Domundos
The Ibiza rental market data above matches what we have lived through this summer in most of our own portfolio, and it is worth putting on the record because it is the part of the story that pacing charts do not show. Most, not all: one villa we manage was caught by the regulatory changes and is having a worse year than any before it, a reminder that the clean-up described above was not free for licensed operators either.
Bookings that came in early, from late winter through spring, went out at strong rates and held. Guests who planned ahead accepted this year’s higher prices without much negotiation, and those reservations stuck. The change came in the final weeks before arrival. Filling last-minute gaps, the odd four or five nights between two longer stays, has been much harder than in any previous season we have managed. Enquiries for those windows arrived later, converted less often and pushed harder on price. Gaps that would have closed within a week in 2024 or 2025 stayed open into the stay month, and some did not fill at all.
We have compared notes with several other villa managers on the island over the past month and the experience is the same across their portfolios: the advance book was healthy, the late book was thin. That is consistent with 28% more villas back on the platforms competing for the same late-deciding guest, and it is the practical reason we are telling owners to reprice September and October now rather than wait for a surge that did not come for the summer gaps either.
The Cross-Check: Other Ibiza Rental Market Trackers Have Not Seen the Turn Yet
AirDNA’s public Ibiza page, updated 1 September, now tracks just 320 active listings and reports supply down 72.4% year on year, with an average daily rate of $486 (+51.7%), occupancy of 50% (+4.9%) and RevPAR of $242 (+40.3%). AirROI’s Market Atlas still shows August figures: 1,904 listings (-20%), ADR $776 (+39%), occupancy 39% (-22%), and annual revenue per listing of $120,214 (+9%). Both count active listings on a trailing-twelve-month basis.
On rate, the three sources agree without hesitation: the Ibiza rental market is charging 20% to 50% more per night than a year ago, depending on currency and panel. On supply, they disagree on direction, and the disagreement is worth explaining rather than hiding. A trailing-twelve-month count of active listings only turns positive once a full year of recovery has passed. AirROI’s own monthly chart already shows the island-wide bottom in January 2026 and a slow climb to 2,800 since, but its headline KPI still compares two trailing years and reads -20%. The trackers should start to show the villa recovery around the end of this year. AirDNA’s panel has also shrunk from 773 to 320 listings in a month, which makes its 258% revenue growth figure a statistical artefact of survivorship rather than a market signal. We would not quote it.
AirROI’s own rate chart supports our reading of the shoulder: booked nights in August cleared at $1,100 to $1,400, while the rate on still-available inventory sat flat at around $850. What is left unsold is priced below what sold, not above it. The market is clearing at the top and stalling at the bottom.
Ibiza Rental Market Forward Look: Autumn Trails, Summer 2027 Leads
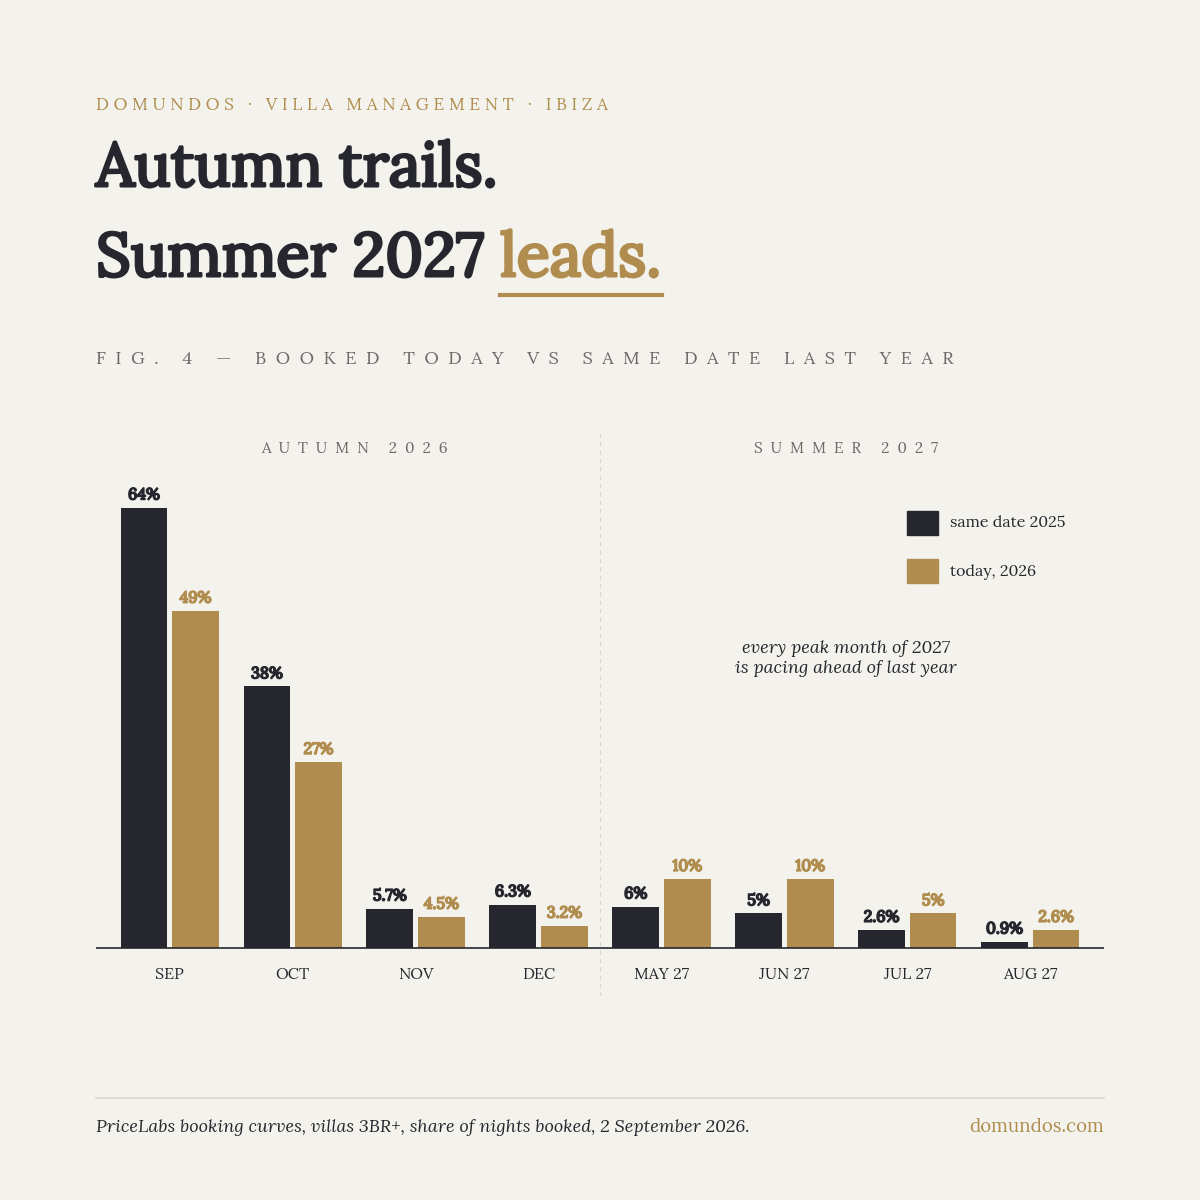
Across the Ibiza rental market, September is 49% booked against 64%, October 27% against 38%. November and December are at 4.5% and 3.2%, against 5.7% and 6.3% at this point last year, all small numbers that will be decided by late bookings. Winter has never been a villa season in Ibiza and the data does not suggest that is changing.
The picture flips for next summer. May 2027 is 10% booked against 6% at this point last year, June 2027 10% against 5%, July 2027 5% against 2.6%, August 2027 2.6% against 0.9%. Every peak month of 2027 is pacing ahead, in several cases at double last year’s rate. The median booking window has stretched to 57 days from 50. The guests who plan Ibiza a year ahead are committing earlier and paying more: asking prices for July and August 2027 are already 25% to 30% above this summer’s levels.
PriceLabs flags five forward windows booking ahead of their surrounding dates: 10 to 12 September (+3.7%), 1 to 4 October (+5.8%), 20 to 23 October (+4.9%), 28 December to 1 January (+3.5%), and 29 May to 2 June 2027 (+4.7%).
Strategy Recommendations for Villa Owners in the Ibiza Rental Market
Drop September rates now, and do it decisively. Across the Ibiza rental market the month is 15 points behind with four weeks to run and asking prices 15% above last year. A 10% to 15% cut on remaining September nights returns your rate to roughly last year’s level, where the market cleared at 72%. Holding out for a July-style late surge is a bet against the arithmetic.
Reprice October before it becomes September. October is 11 points behind with asking rates 22% above last year. Bring October to last year’s rate plus 5% to 8%, not plus 22%. The demand for a 61% October exists; it is not paying a fifth more for it.
Do not touch summer 2027. Every peak month next year is pacing ahead of this year, with asking prices 25% to 30% higher already accepted by early bookers. The summer market has proved it can absorb both more supply and higher rates. Set 2027 peak rates at this summer’s achieved ADR plus 15% and leave them.
Load the five spike windows. The October long weekends (1 to 4 and 20 to 23 October) are booking ahead of their neighbours even in a soft October. Carry a premium there while discounting the surrounding dates.
Switch to dynamic pricing if you have not. Dynamically priced listings are 37% of the market and take 43% of bookings. In a month like September, a static rate set in spring is the single most expensive decision an owner can make.
Firm up cancellation terms on autumn stays. With cancellations running level with new bookings for September and October, and outnumbering them by more than two to one for the winter, a moderate or firm policy is the difference between a booking and a placeholder.
Want to know what these numbers mean for your own villa? Run it through the Ibiza villa income calculator or talk to us.
Sources
PriceLabs Market Dashboard and raw market data, Ibiza, Airbnb full market, villas with three or more bedrooms, data date 2 September 2026. AirDNA public Ibiza market overview, updated 1 September 2026. AirROI Market Atlas, Ibiza viewport, retrieved 3 to 5 September 2026 (KPIs still showing August data; monthly active-listings chart through September 2026). Domundos monthly report archive, June to August 2026. Reporting on the Ibiza short-term rental licensing framework and the platform clean-up: Periódico de Ibiza, Ibiza the first region cleaned up of illegal Airbnb listings (September 2025); Última Hora, Airbnb to remove Ibiza listings without a registration number (June 2025); Tribunal Supremo press note, annulment of the national short-let register (May 2026); Off Market Ibiza, Licencias Turísticas en Ibiza 2026; Observatorio Ibiza de Edificación, Registro obligatorio del alquiler de corta duración.
Published monthly by Domundos. Data reflects Ibiza rental market conditions for villas as of 2 September 2026. From September 2026 the PriceLabs reference set covers the full Ibiza Airbnb market, villas with three or more bedrooms (1,303 active listings). Earlier reports used a Jesús-centred set including apartments and are not directly comparable.