
We Told Owners to Cut September. The Market Held Its Price and Filled Anyway.
In one line: The Ibiza rental market closed September at 73% occupancy, two points below last year, at €884 a night, 19% more than last September, after booking 24 points of occupancy in the final four weeks; October is ten points behind at 43%, winter cancellations now outnumber new bookings, and every peak month of 2027 is pacing at roughly double last year’s rate.
Domundos / Market Reports / October. Monthly analysis of the Ibiza rental market for villa owners. Data: PriceLabs market data for the full Ibiza market, villas with three or more bedrooms (10 October 2026), AirDNA and AirROI market trackers (6 to 10 October 2026), Aena, Ibestat, FEHIF, Domundos report archive.
TL;DR
- September 2026 closed at 73% occupancy against 75% last year, at an average daily rate of €884, up 19% on September 2025. Revenue per available villa for the month rose 15% to €17,159. On 2 September the month was 49% booked, 15 points behind last year. It added 24 points in four weeks; last September added 11
- Last month this report recommended a 10% to 15% rate cut for September. Owners who held their rate were right. Asking prices for September nights stayed 15% above last year and the market cleared at that price. Total booked nights in September rose 25% year on year on 32% more listings
- October is 43% booked against 53% at the same date last year, with asking rates 14% higher. The first nine nights of October closed at 68% against 75%; the rest of the month is 33% booked against 45% at this point last year. Last October finished at 63%
- Winter is cancelling faster than it books. Over the past 30 days the Ibiza rental market recorded 358 cancellations against 242 new bookings for November to March stays. For December, cancellations outnumber new bookings 103 to 55
- Every peak month of 2027 is pacing ahead of last year, most at double the rate: June 2027 is 16% booked against 9% at this point last year, July 12% against 6%, May 15% against 10%. Asking prices for June to August 2027 are 21% to 27% above this summer’s
- Trailing twelve months, the villa segment is up on every KPI: ADR €849 (+17%), RevPAR €541 (+18%), bookings 33,840 (+21%), estimated revenue per listing €136,770 (+15%), booking window 55 days (+5), occupancy 64% (+1 point), active listings 1,303 (+255)
Market Conditions: The Ibiza Rental Market Fills Later Than We Thought Possible
The most useful thing this report can do this month is correct itself. On 2 September, with September 49% booked against 64% at the same date in 2025, we wrote that “the arithmetic does not support holding rate” and told owners to drop September prices by 10% to 15%. The arithmetic was based on how September had behaved before: last year the month gained about 11 points of occupancy in its final four weeks. This year it gained 24. September closed at 73%, two points below last year’s 75%, at an average daily rate of €884, up €141 or 19% on September 2025. Revenue per available villa for the month came in at €17,159, up 15%. Owners who ignored our advice and held their price did better than owners who followed it.
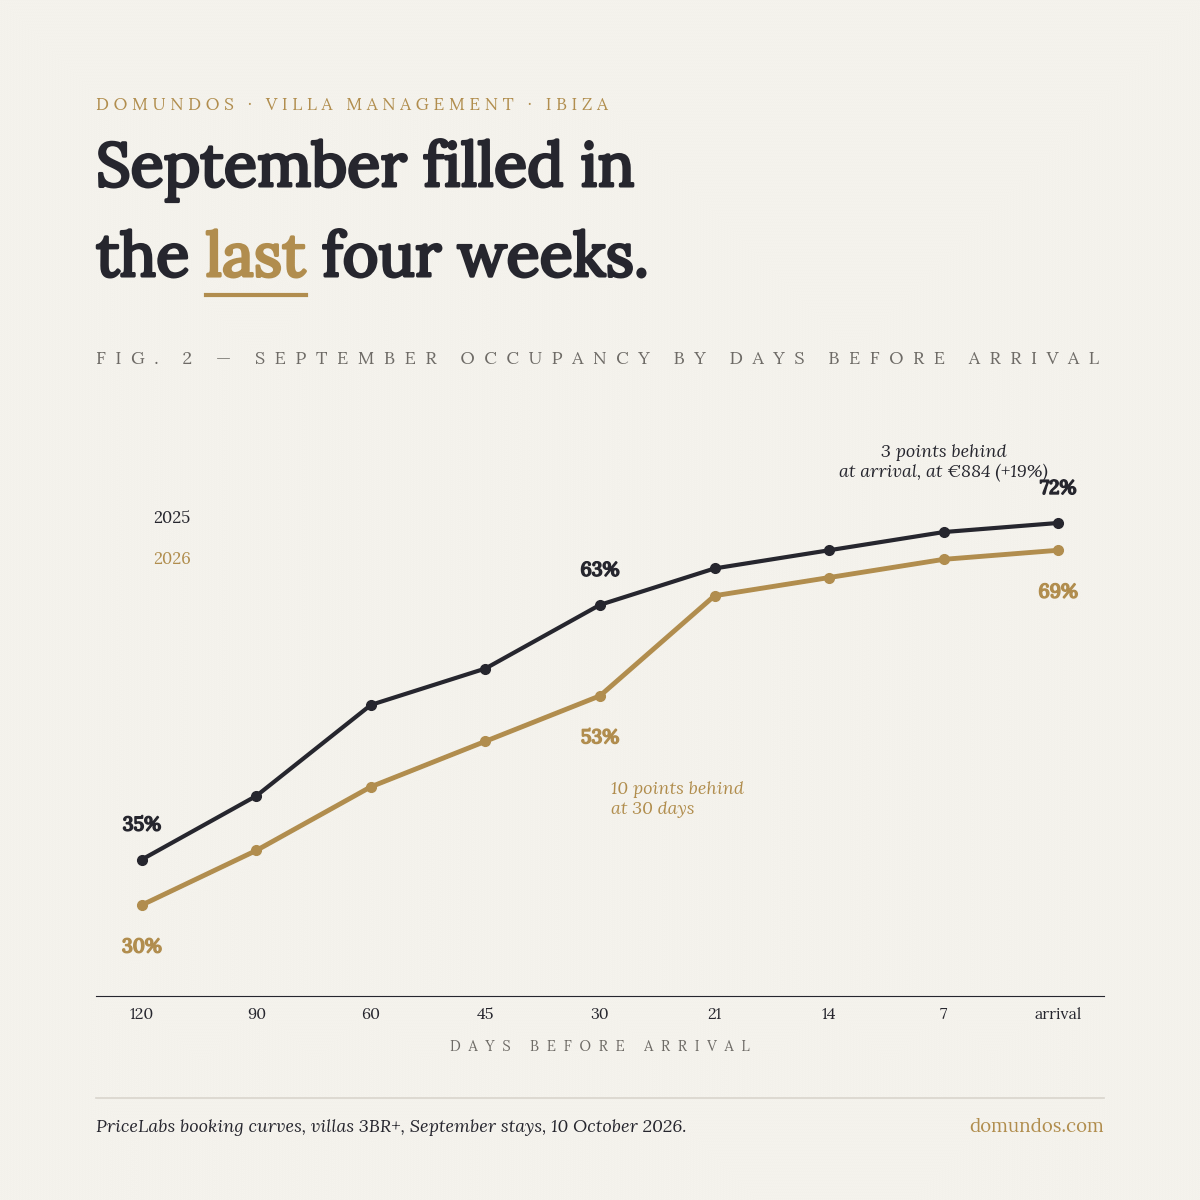
What happened is not a mystery once the numbers are laid side by side. Total booked nights in September rose 25% year on year, to 21,417, on 32% more active listings. The demand was there; it simply arrived later than any September we have measured. The booking curve shows the shift exactly. At 60 days out September 2026 was 43% booked against 52% last year. At 30 days it was 53% against 63%. At 21 days the gap had closed to three points, 64% against 67%, and it stayed at three points through to arrival. The median booking window for September stays was 59 days, against 72 days last year. The month did not lose guests to the restored inventory. It lost lead time.
The rate held across every size of villa. A 3-bedroom averaged €524 a night in September, up 17%. A 4-bedroom averaged €764, up 14%. A 5 to 6-bedroom averaged €1,230, up 25%. Occupancy slipped a few points in the smaller bands, 78% against 83% for 3-bedrooms and 73% against 76% for 4-bedrooms, and was level for 5 to 6-bedrooms at 69%. In every band the rate gain was larger than the occupancy loss, which is why revenue per villa rose in all of them.
The hotel sector reports the same shape of month. The Ibiza and Formentera hotel federation closed September at 86.9% occupancy against 87.9% a year earlier, with the second half of the month weaker than the first, and summed up its season as having “grown in value while the growth in occupancy has moderated”. Spend data points the same way: Ibestat counted 699,937 tourists on Ibiza and Formentera in August, 4.4% more than in August 2025, spending €243 a day each, 8.8% more, while overnight stays fell 1.9%. More people, paying more per night, staying fewer nights, deciding later. That is the 2026 guest, and the villa market is now priced for them.
Across the trailing twelve months the Ibiza rental market’s villa segment is ahead on every headline metric: an average daily rate of €849 (+17%), RevPAR of €541 (+18%), 33,840 bookings (+21%), estimated revenue per listing of €136,770 (+15%), a median booking window of 55 days (+5) and occupancy of 64%, one point ahead of last year, on 1,303 active listings, 255 more than a year ago. For a segment that re-absorbed a quarter of its inventory inside a year, that is an exceptional set of numbers, and September was the month that proved the summer’s pricing was not a peak-season fluke.
The Feature: Winter Is Cancelling Faster Than It Books
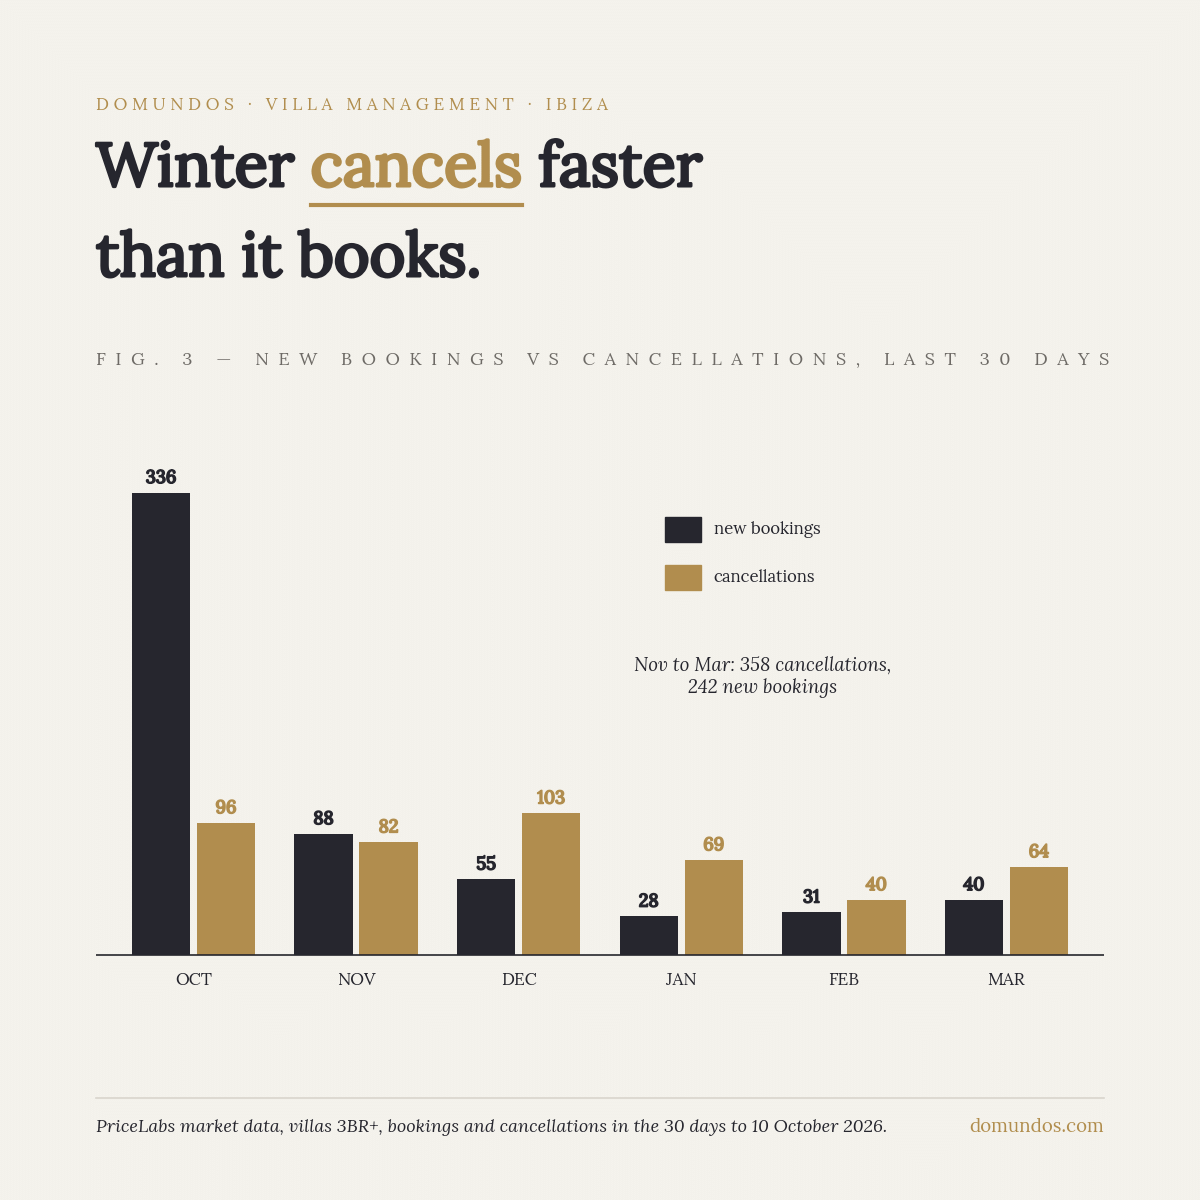
If September showed where demand in the Ibiza rental market is deeper than expected, the winter calendar shows where it is thinner. Over the past 30 days the market recorded 358 cancellations for stays between November and March against 242 new bookings. For December alone, 103 bookings were cancelled and 55 made. For January, 69 cancelled and 28 made. November is the only winter month where the two are roughly level, 82 cancellations to 88 new bookings. A villa calendar that shows a December booking today has a meaningful chance of showing a gap by the time the guest was due to arrive.
The pacing numbers are small, but they are behind. November is 9% booked against 10% at this point last year, with last November finishing at 23%. December is 6% against 9%, on its way to a 26% final last year. The Christmas and New Year week, 28 December to 2 January, is 9% booked against 13% at the same date last year; it finished at 43% last year. PriceLabs still flags that week as booking ahead of its surrounding dates, by 4.6%, so there is a market for it. It is just not committing yet, and some of the guests who did commit have changed their minds.
Two things are working against the winter book at the same time. The first is the price gap. The median listed price for a December night is €942, against a median booked price of €526 for the few December bookings that exist. Owners are asking summer-shoulder money for a month that last year cleared at €500 a night. The second is policy. Across the market, 49% of listings use a firm cancellation policy, which refunds in full up to 30 days before arrival, and 37% a strict one, which keeps half. A December stay cancelled in October costs the guest nothing on a firm policy and half the booking on a strict one, and firm listings take 58% of the market’s bookings. Most of the winter churn is therefore free to the guest, which is why it is invisible until it has already happened.
October sits between the two stories. The month is 43% booked today against 53% at the same date last year, with the first nine nights having closed at 68% against 75%, and the remaining three weeks 33% booked against 45% at this point last year. Last October finished at 63%, and the remainder of the month finished at 56%. Asking rates for October are 14% above last year at the median, and the rate actually being paid is 20% higher, €658 against €549. October has a healthy ratio of 336 new bookings to 96 cancellations over the past 30 days, and the long weekend of 20 to 24 October is booking 6.3% ahead of its surrounding dates. If September is the guide, October will close most of its gap in the final three weeks. If December is the guide, it will not. The honest answer is that October is the first month in which the late-book pattern meets genuinely seasonal demand, and nobody, including us, knows which side wins.
One number has moved decisively since last month. Listings with a high or moderate dynamic pricing strategy now make up 46% of the Ibiza rental market and take 57% of its bookings. Listings with no pricing strategy make up 27% and take 19%. In September the same split was 37% of listings taking 43% of bookings against 37% taking 33%. In a month that fills in its final four weeks, the listing that reprices daily is the listing that fills.
From the Front Line: What We Are Seeing at Domundos
September in our own portfolio followed the market almost exactly. The gaps we were worried about at the start of the month, the four and five-night windows between longer stays, filled in the final two weeks at rates we had not discounted, and in two cases at rates above what the same week achieved in 2025. The enquiries came late, often within ten days of arrival, and they converted at full price more often than in July and August, when the late enquiries pushed harder on rate. We did reprice a handful of October nights in line with last month’s advice and would not do so again on the evidence above.
What we are watching now is the winter book. We have had two December cancellations in the past month across the villas we manage, both made in early summer, both refunded in full under the policy they were booked on. Neither has been replaced yet. We have also started to receive the first enquiries for Easter and May 2027 at prices 20% above this year’s, which matches the pacing data below.
The Cross-Check: What Other Ibiza Rental Market Trackers See
PriceLabs’ own whole-island Airbnb set, which includes apartments and smaller homes, counts 2,820 active listings, 155 fewer than a year ago. That is the first time this report can quote a like-for-like island-wide Airbnb count, and it agrees with AirROI, whose Ibiza viewport counted 2,800 listings last month and shows 1,708 active listings on its trailing-twelve-month basis today, down 19% on a year ago. Entire-home listings in that panel fell from about 2,200 in September 2025 to about 1,500, and private rooms from 375 to 144. AirROI reports annual revenue per listing of $130,123 (+10%), an average daily rate of $809 (+33%) and trailing occupancy of 40% (-18%), with 84% of listings now displaying a registration number. Its median occupancy for September 2026 was 43.3% against 46.7% a year earlier.
AirDNA’s public Ibiza page, updated 6 October, now tracks only 268 listings, down 74% year on year, and reports an average daily rate of $613 (+93%), occupancy of 44% (-4.5%) and RevPAR of $270. Its panel has shrunk from 773 listings in August to 320 in September and 268 now, so its growth figures measure which listings survived rather than how the market moved. We quote it for completeness and would not build an argument on it.
The three sources agree on direction. The island has fewer listings than a year ago, those listings charge far more per night, and occupancy across all property types is flat to down while the licensed villa segment that this report tracks is flat to up. The villa segment is outperforming the island, and the trackers that mix villas with apartments and rooms are showing the drag from the rest.
Ibiza Rental Market Forward Look: October Trails, Winter Thins, Summer 2027 Leads
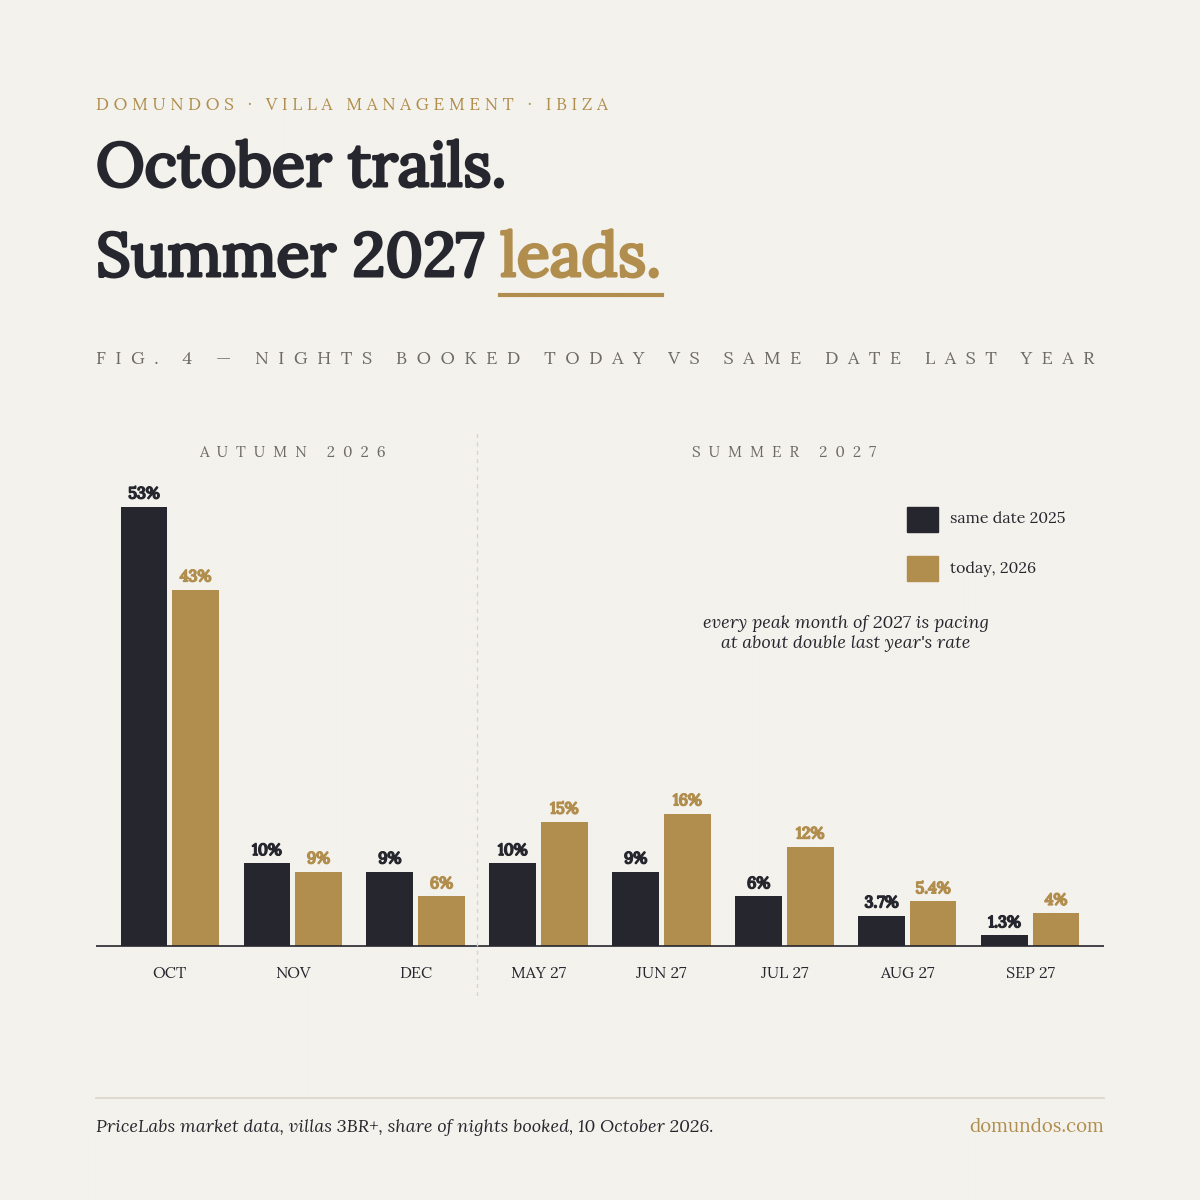
Across the Ibiza rental market, October is 43% booked against 53%, November 9% against 10%, December 6% against 9%, January 2.6% against 2.7%. The shoulder is behind and the winter is level on small numbers.
The picture for next summer is the strongest we have recorded. May 2027 is 15% booked against 10% at this point last year. June 2027 is 16% against 9%. July is 12% against 6%, August 5.4% against 3.7%, September 2027 4% against 1.3%. Every peak month is pacing at or near double last year’s rate, and the price those early bookers are accepting is higher: the median asking rate for a June 2027 night is €1,301 against €1,025 for June 2026, July 2027 €1,511 against €1,248, August 2027 €1,559 against €1,270, rises of 21% to 27%. The guest who plans Ibiza a year ahead is paying this summer’s achieved rate plus a fifth, and doing it eight months early.
PriceLabs flags five forward windows booking ahead of their surrounding dates: 20 to 24 October (+6.3%), 28 December to 2 January (+4.6%), 29 April to 6 May 2027 (+2.9%), 29 May to 1 June 2027 (+5.1%) and 24 to 27 July 2027 (+3.1%).
Two external items matter for 2027 planning. Aena handled 1,519,201 passengers at Ibiza airport in August, 2.5% more than last August, and 6,778,163 in the first eight months of the year, up 3%; the growth is domestic (+6%) rather than international (+0.8%). And the Spanish government’s housing decree of 6 October 2026, now in force but still awaiting its parliamentary vote, would apply 10% VAT to furnished rentals of 30 nights or less from 1 December 2026. The Balearic government has said it is studying a constitutional challenge. If it stands, a €1,000 night in 2027 will carry €100 of VAT that it does not carry today, and owners should decide now whether that comes out of the rate or goes on top of it.
Strategy Recommendations for Villa Owners in the Ibiza Rental Market
Hold October rates until the final three weeks, then reprice by the week, not by the month. September proved that the late book clears at full price when the rate is right for the week. October is ten points behind with asking rates 14% above last year; the gap is in the second half of the month. Carry the premium on the 20 to 24 October weekend and bring the surrounding midweek nights to last year’s rate plus 5%. Do not cut the whole month.
Price December at last year’s achieved rate, not at October’s asking rate. The median listed December night is €942 against a median booked price of €526. That gap is why the month is 6% booked with cancellations running two to one against new bookings. Set December at €500 to €550 for a standard 3 to 4-bedroom villa and let the Christmas week carry a 30% premium on top.
Rebook every cancelled winter stay within the week. With 358 winter cancellations against 242 new bookings in 30 days, a cancellation left for a month is a cancellation that stays. Re-list the dates the day they free up, at a rate 10% below the one that cancelled.
Raise summer 2027 now. Every peak month is pacing at double last year’s rate at asking prices 21% to 27% above this summer. Set June to August 2027 at this summer’s achieved ADR plus 20% and leave them. The early bookers have already accepted that price.
Switch to dynamic pricing before the next shoulder, not after. Dynamically priced listings are 46% of the market and take 57% of bookings; static listings are 27% and take 19%. In a market that books its shoulder months in the final four weeks, a static rate set in spring is now the single largest cost an owner carries.
Decide the VAT question before you publish 2027 rates. If the 10% VAT on short stays survives its parliamentary vote, it applies from 1 December. Build it into the 2027 rate card now rather than absorbing it later.
Want to know what these numbers mean for your own villa? Run it through the Ibiza villa income calculator or talk to us.
Sources
PriceLabs Market Dashboard and raw market data, full Ibiza Airbnb market, villas with three or more bedrooms, data refreshed 9 October 2026 and exported 10 October 2026; PriceLabs Airbnb whole-island set for the island-wide listing count. AirDNA public Ibiza market overview, updated 6 October 2026. AirROI Market Atlas, Ibiza viewport, retrieved 10 October 2026. Domundos monthly report archive, June to September 2026. Aena August 2026 passenger figures via La Voz de Ibiza. Ibestat August 2026 tourist arrivals and spend via La Voz de Ibiza. FEHIF September 2026 hotel occupancy via Periódico de Ibiza. Royal Decree-Laws 28/2026 and 29/2026 on housing and the 10% VAT on short stays via Última Hora. Consell d’Eivissa enforcement figures via La Voz de Ibiza.
Published monthly by Domundos. Data reflects Ibiza rental market conditions for villas with three or more bedrooms as of 10 October 2026. The PriceLabs reference set is the full Ibiza Airbnb market, villas 3BR+ (1,303 active listings); reports before September 2026 used a Jesús-centred set including apartments and are not directly comparable.